The Biggest Credit Hurdle for Renters Who Want To Buy
What's the biggest payment you make every month? If you’re a renter, it's probably your rent.
But did you know that you can pay your rent on time, every time, for years, and it may never show up in your credit history? It's pretty frustrating, especially if you'd like to buy a home someday and you’re trying to build your credit.
The good thing is that’s changing right now. Here’s what you need to know and why it could open a door you thought was closed.
The Problem for Would-Be Buyers
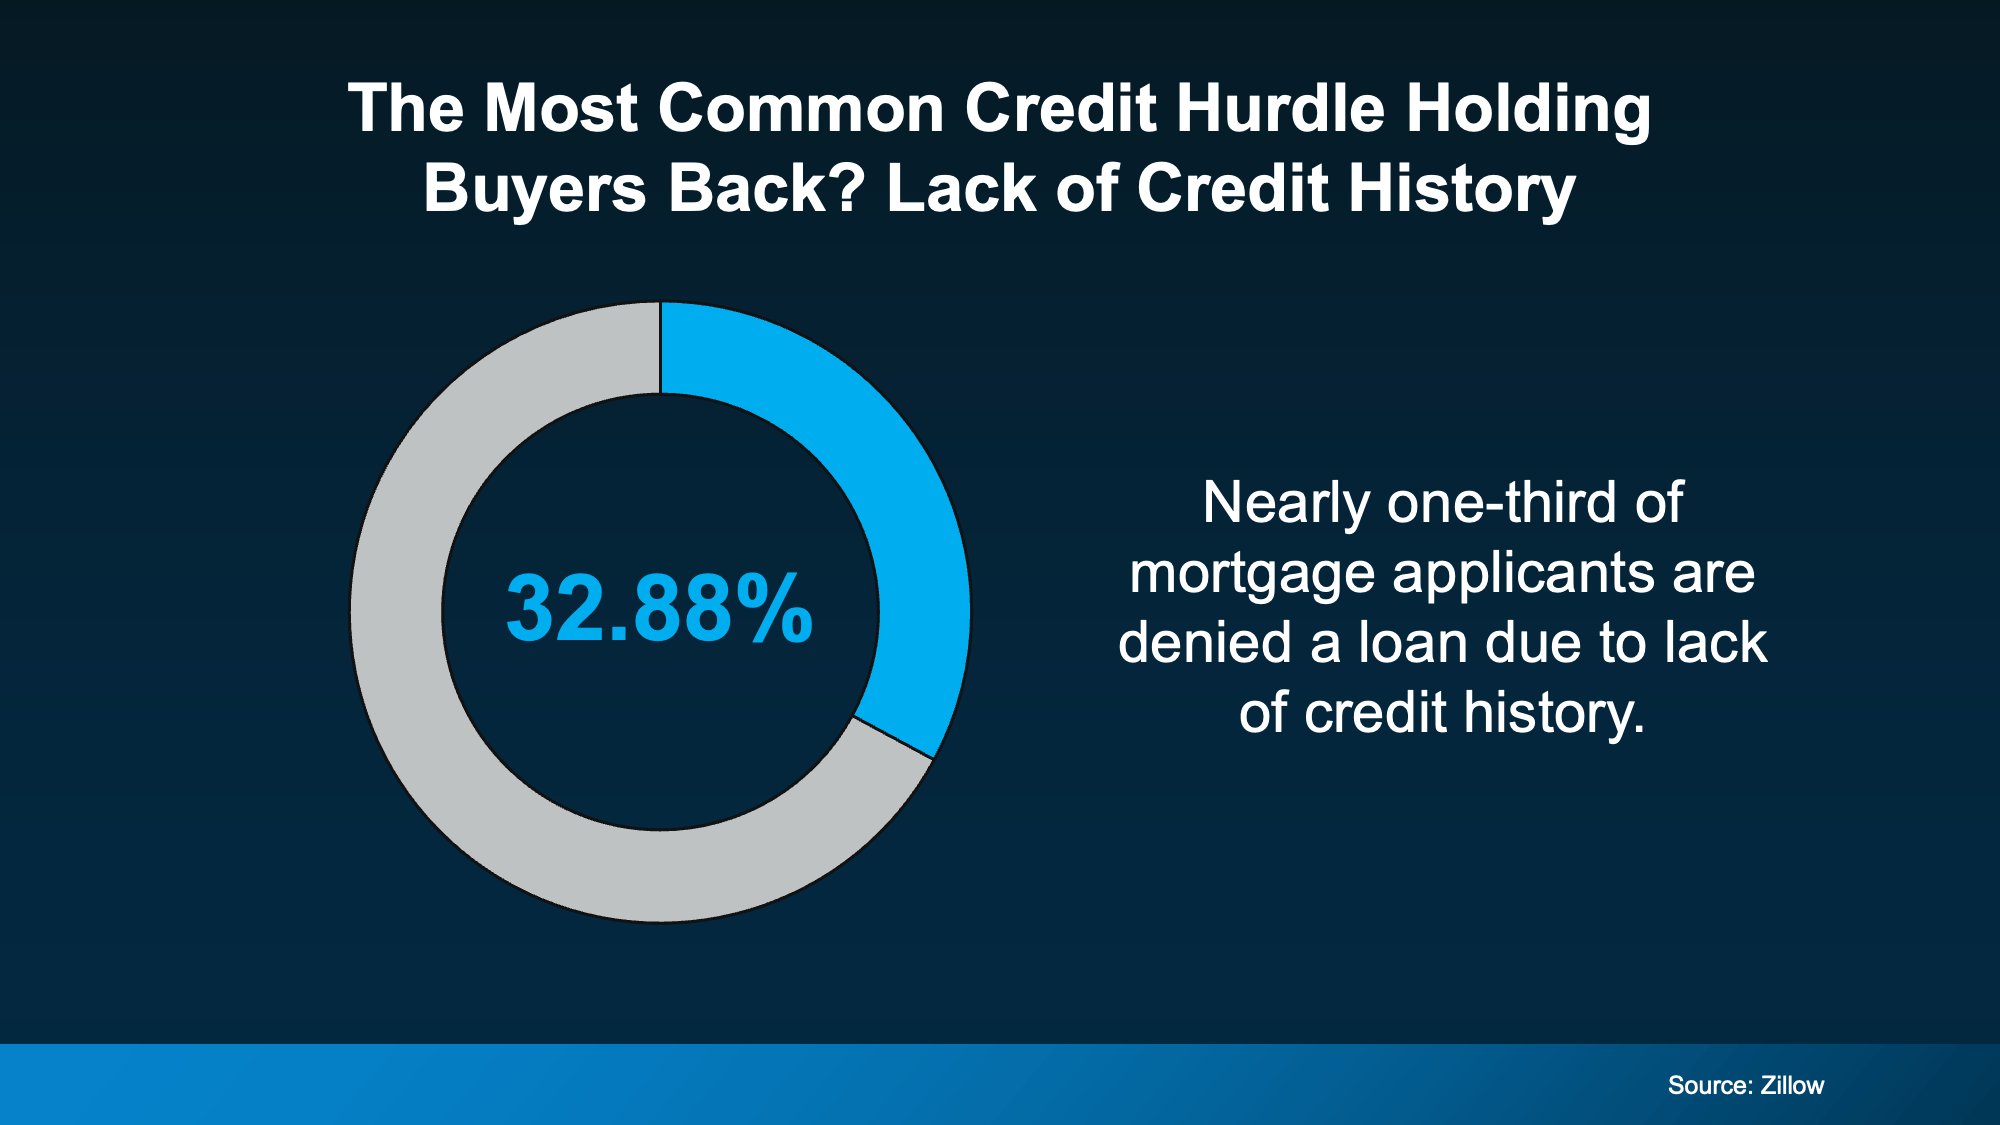
You’re not the only one frustrated. According to Zillow, nearly a third of applicants (32.88%) get denied a mortgage due to insufficient credit history - not missed payments or too much debt. Just not enough credit history for a lender to say "yes."
It’s the most common hurdle would-be buyers have. As Zillow explains:
“Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history, making it the most common reason for a denial.”
But there’s finally a way in now that how credit gets measured is changing.
The Good News: Credit Is Getting Broader
As Michael Sherman, General Manager and Senior VP at Zillow Rentals, explains:
"Affordability is the headline in housing right now, and access to financing is a very important part of the story. Credit history is a barrier standing in the way of too many potential buyers. Rent reporting is a direct way to address that.”
Here’s what Sherman is talking about. New credit models are emerging that take on-time rent and some utility payments into consideration to help renters get credit for the bills they already pay.
VantageScore is one company with a new credit model that has been approved for use by the Federal Housing Finance Agency (FHFA). And that roll out could have a big impact on renters like you.
A recent study by VantageScore found that nearly 4 million U.S. renters could finally become eligible for a mortgage if their on-time rent payments were counted as part of their credit history. Now, this isn’t a guarantee that it will suddenly count for every would-be buyer, but it does crack open the door.
Here’s the catch though, you still have to walk through it.
Counting Rental Payment History Is Not Automatic
There are more options available to build credit, but you have to be proactive. Your rent won't necessarily count unless you make sure it does. And the sooner you take credit for your payments, the better.
Here's how to get started based on a few tips from Experian, the Consumer Financial Protection Bureau (CFPB), and FICO:
-
Ask your landlord or property manager if your rent is being reported. If it's not, opt in.
-
If your landlord doesn't offer rent reporting, there are services available. Be sure to check fees and which bureaus they provide your data to.
-
Check your credit reports for errors. Mistakes happen and fixing them is one of the quickest ways to strengthen your profile. The CFPB offers step-by-step instructions on how to fix errors on your report.
-
Follow basic, important credit rules. Pay your bills on time, keep your card balances low, and don't apply for a bunch of new credit at once.
-
Don’t close any accounts - even if you have paid them off and don't use them often.
-
Diversify your profile by getting a secured credit card or becoming an authorized user on someone else's account to help you build history beyond rent.
These steps take a little time and effort, but it could be worth it if it starts building up your credit history.
Just remember, not every lender uses the same scoring model and there are more changes on the horizon. So, the sooner you get credit for the work you do, the better.
Even if you're not sure when you might be ready to buy a home, talking to a lender is a good place to start. A professional loan officer will help you make a plan and help you figure out a timeline to get ready to officially apply and buy.
Bottom Line
The credit landscape is changing, but action is required on your part. You have to take credit for what you do. And the sooner you get started, the better.
Ready to see where you stand? A quick conversation with a loan officer costs you nothing and could show you you're closer to owning a home than you think.
Categories
- All Blogs (191)
- Credit Scores & First-Time Home Buyers (1)
- Emotional Value of Homeownership (1)
- First-Time Buyer Guidance (1)
- First-Time Home Buyers & Affordability (1)
- First-Time Homebuyers (12)
- First-Time Homebuyers & Affordability (1)
- First-Time Homebuyers & Market Trends (1)
- Home Affordability & Relocation (1)
- Home Buying (5)
- Home Buying & Down Payment Strategy (1)
- Home Buying & Housing Market (1)
- Home Buying & Real Estate Strategy (1)
- Home Buying & Remote Work (1)
- Home Buying & Selling (1)
- Home Buying & Selling | Mortgage Rates | Real Estate Market (1)
- Home Buying & Selling Strategy (1)
- Home Buying & Selling Tips (1)
- Home Buying Preparation (1)
- Home Buying Strategy (1)
- Home Buying Tips (11)
- Home Buying Trends (1)
- Home Buying Trends & Strategies (1)
- Home Equity (2)
- Home Equity & Selling (1)
- Home Financing / First-Time Buyers (1)
- Home Prices & Buyer Opportunities (1)
- Home Prices & Housing Market (1)
- Home Prices & Market Trends (2)
- Home Prices & Real Estate Market (1)
- Home Seller Motivation (1)
- Home Selling (3)
- Home Selling & Fall Real Estate (1)
- Home Selling & Home Value (1)
- Home Selling & Housing Market (1)
- Home Selling & Housing Market Trends (1)
- Home Selling & Market Trends (1)
- Home Selling & Negotiation Strategies (1)
- Home Selling & Pricing Strategy (1)
- Home Selling & Real Estate Tips (1)
- Home Selling & Staging Tips (1)
- Home Selling Advice (4)
- Home Selling Strategy (1)
- Home Selling Tips (15)
- Home Selling Tips & Market Trends (3)
- Homebuyer Guides (1)
- Homebuyer Tips (2)
- Homebuying & Affordability Solutions (1)
- Homebuying Tips (1)
- Homeownership & Real Estate Investment (1)
- Homeownership Costs (1)
- Homeownership Tips (1)
- Housing Affordability & Mortgage Rates (1)
- Housing Inventory & Mortgage Rates (1)
- Housing Market & Foreclosure Trends (1)
- Housing Market & Home Buying (4)
- Housing Market & Home Selling (1)
- Housing Market & Home Values (1)
- Housing Market & Homeowner Equity (1)
- Housing Market Forecast (2)
- Housing Market Forecast & Real Estate Trends (1)
- Housing Market Insights (8)
- Housing Market Tips (1)
- Housing Market Trends (4)
- Housing Market Updates (23)
- Inflation, Mortgage Rates & Housing Market (1)
- Life Transitions & Homebuying Decisions (1)
- Luxury Real Estate (1)
- Market Trends & Forecasts (1)
- Market Trends & Insights (1)
- Market Update (1)
- Mortgage & Affordability (1)
- Mortgage & Finance (1)
- Mortgage & Financing (1)
- Mortgage & Home Buying (1)
- Mortgage & Interest Rates (1)
- Mortgage Rates & Federal Reserve (1)
- Mortgage Rates & Home Buying (1)
- Mortgage Rates & Home Buying Strategy (3)
- Move-Up Buyers (1)
- Moving & Selling Tips (1)
- New Construction (1)
- New Construction & Home Buying (1)
- New Construction & Homebuying (1)
- Real Estate / Housing Market (1)
- Real Estate Investing (1)
- Real Estate Market Insights & Homebuying (1)
- Real Estate Market Trends (1)
- Real Estate Market Update (5)
- Real Estate Trends (2)
- Retirement & Housing Decisions (1)
- Retirement & Real Estate (1)
- Seasonal Real Estate Trends (1)
- Seller Education & Market Insights (1)
- Selling a Home & Housing Market (1)
- Selling Tips (2)
- Senior Living & 55+ Communities (1)
- Senior Living & Downsizing (1)
- Strategy & Re-listing Tips (1)
- VA Loans & Veteran Homebuying (1)
Recent Posts
Associate Broker License ID: BR526609000
+1(602) 342-8006 | andrewm@themonaghangroup.com