Why More Buyers Are Turning To Adjustable-Rate Mortgages Today
When mortgage rates climb, buying a home can start to feel like trying to hit a moving target. Every jump in rates makes monthly payments bigger, and that pushes a lot of buyers to look for another way in.
More and more of them are finding it in the adjustable-rate mortgage, or ARM.
The ARM Option
Here’s how an ARM differs from a more traditional mortgage. With a regular fixed-rate mortgage, your rate stays the same for your whole loan. But with an ARM, your rate is locked for the first few years, then it can move up or down based on market conditions.
Some people don’t like that level of uncertainty – and that’s okay. But others are drawn to this option specifically because there’s usually a lower rate to start when you opt for an ARM. And in an affordability-strapped market, that’s going to gain popularity.
Bankrate recently found that, in September, rates for ARM products were over a full percentage point lower than a regular fixed-rate loan. Depending on the ARM product, that can make a difference of $150-300 in the monthly payment on a median-priced home.
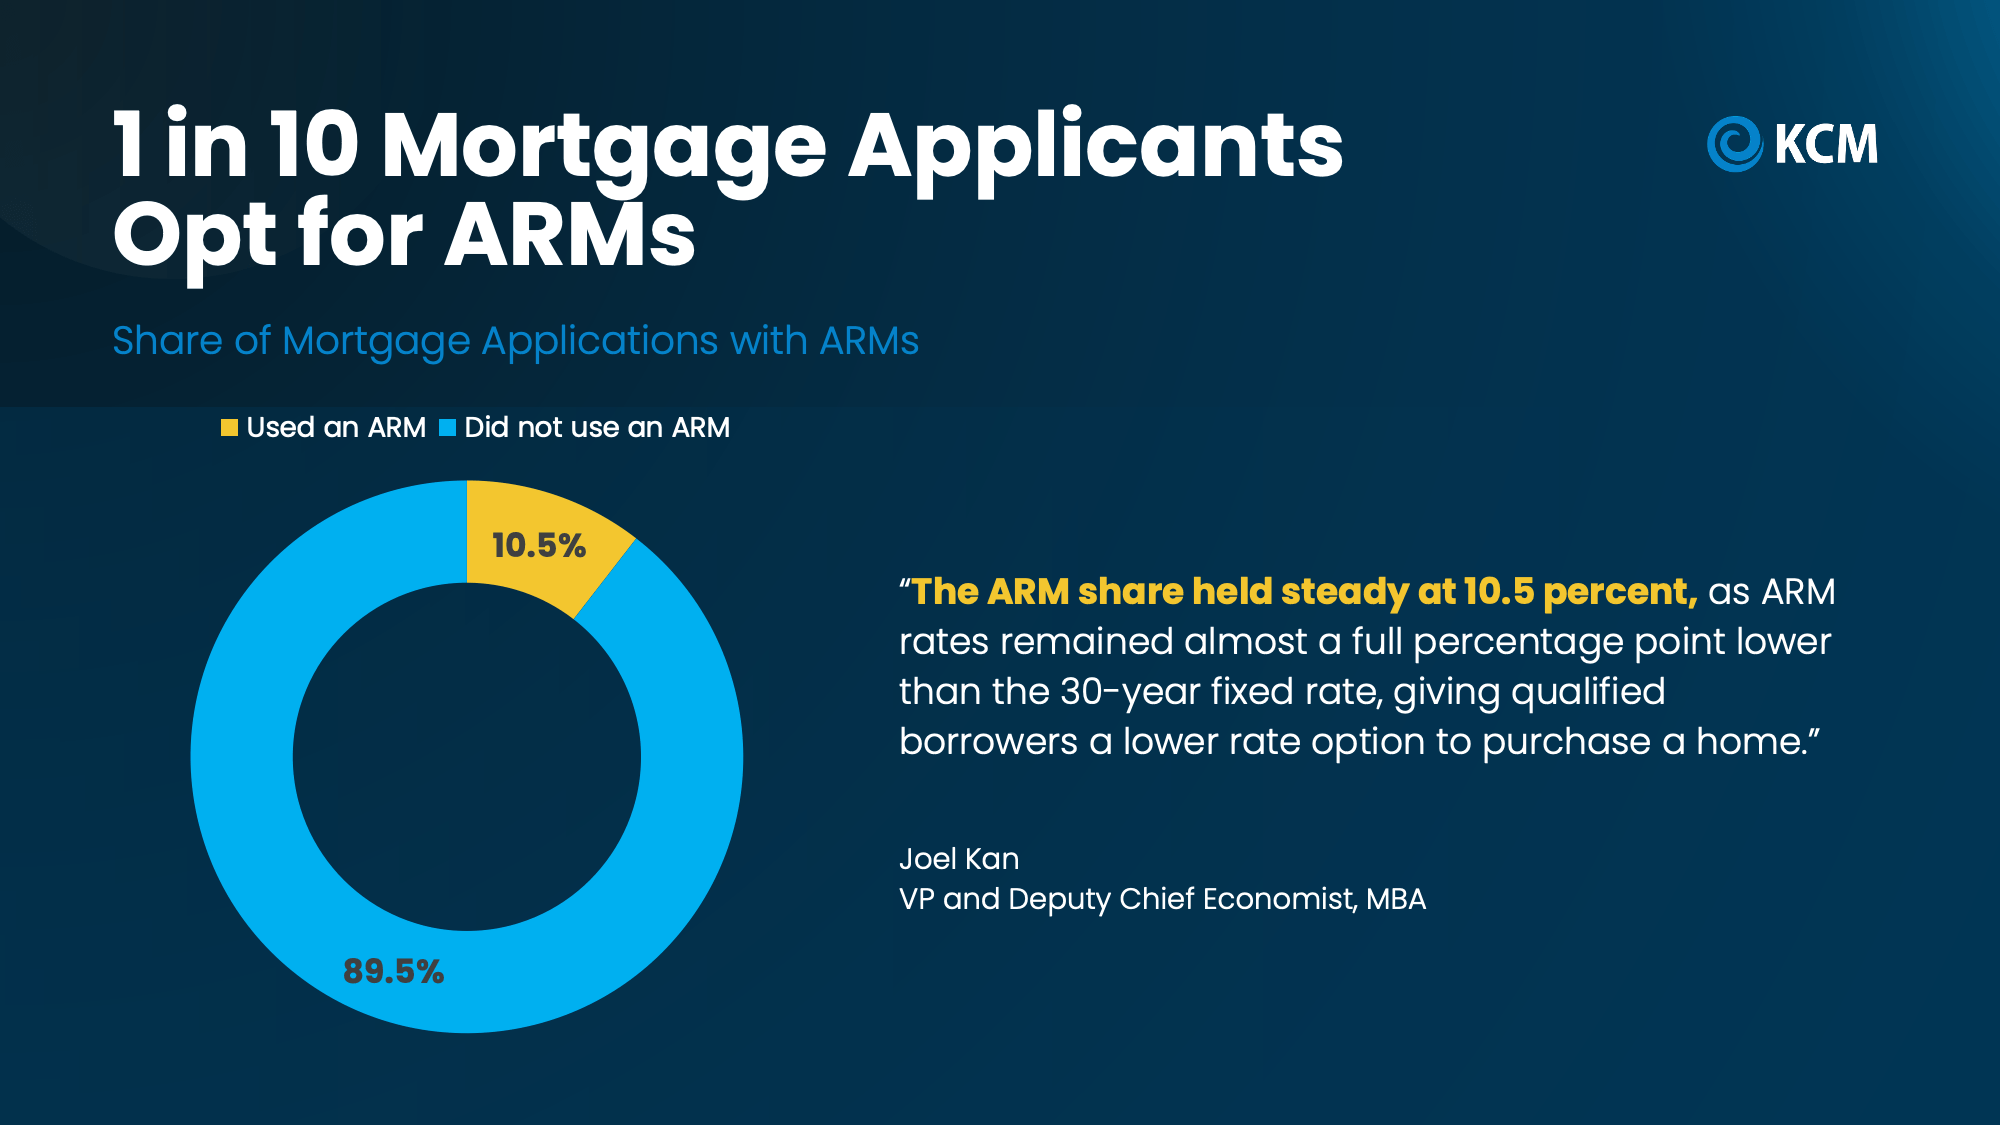
And for some buyers, that’s enough to turn “not right now” into “let’s do this.” You can see it in the numbers. Data from the Mortgage Bankers Association (MBA) shows that, in October, roughly 1 in 10 people applying for a mortgage chose an ARM (see graph below):
If you think you may want to consider this yourself, here’s what you need to know about how it works.
The 5/1 ARM
An ARM is like a phone or cable plan that has an introductory deal for new customers. You start out at a lower price, and then it adjusts after a specified amount of time. A popular loan is the 5/1 ARM.
The "5" means your introductory rate is locked for the first five years, and the "1" means that the rate can change every year after that. The rate change is called the "reset." And here’s the really important part.
When your rate resets, your mortgage payment could go up or down. The good news is that most ARMs have caps, which are limits on how much your rate can rise each year and over the life of the loan. But either way, you have to be ready.
The Upsides and Potential Downsides
To see if this type of loan may be right for you, here are some things to think about and discuss with your loan officer:
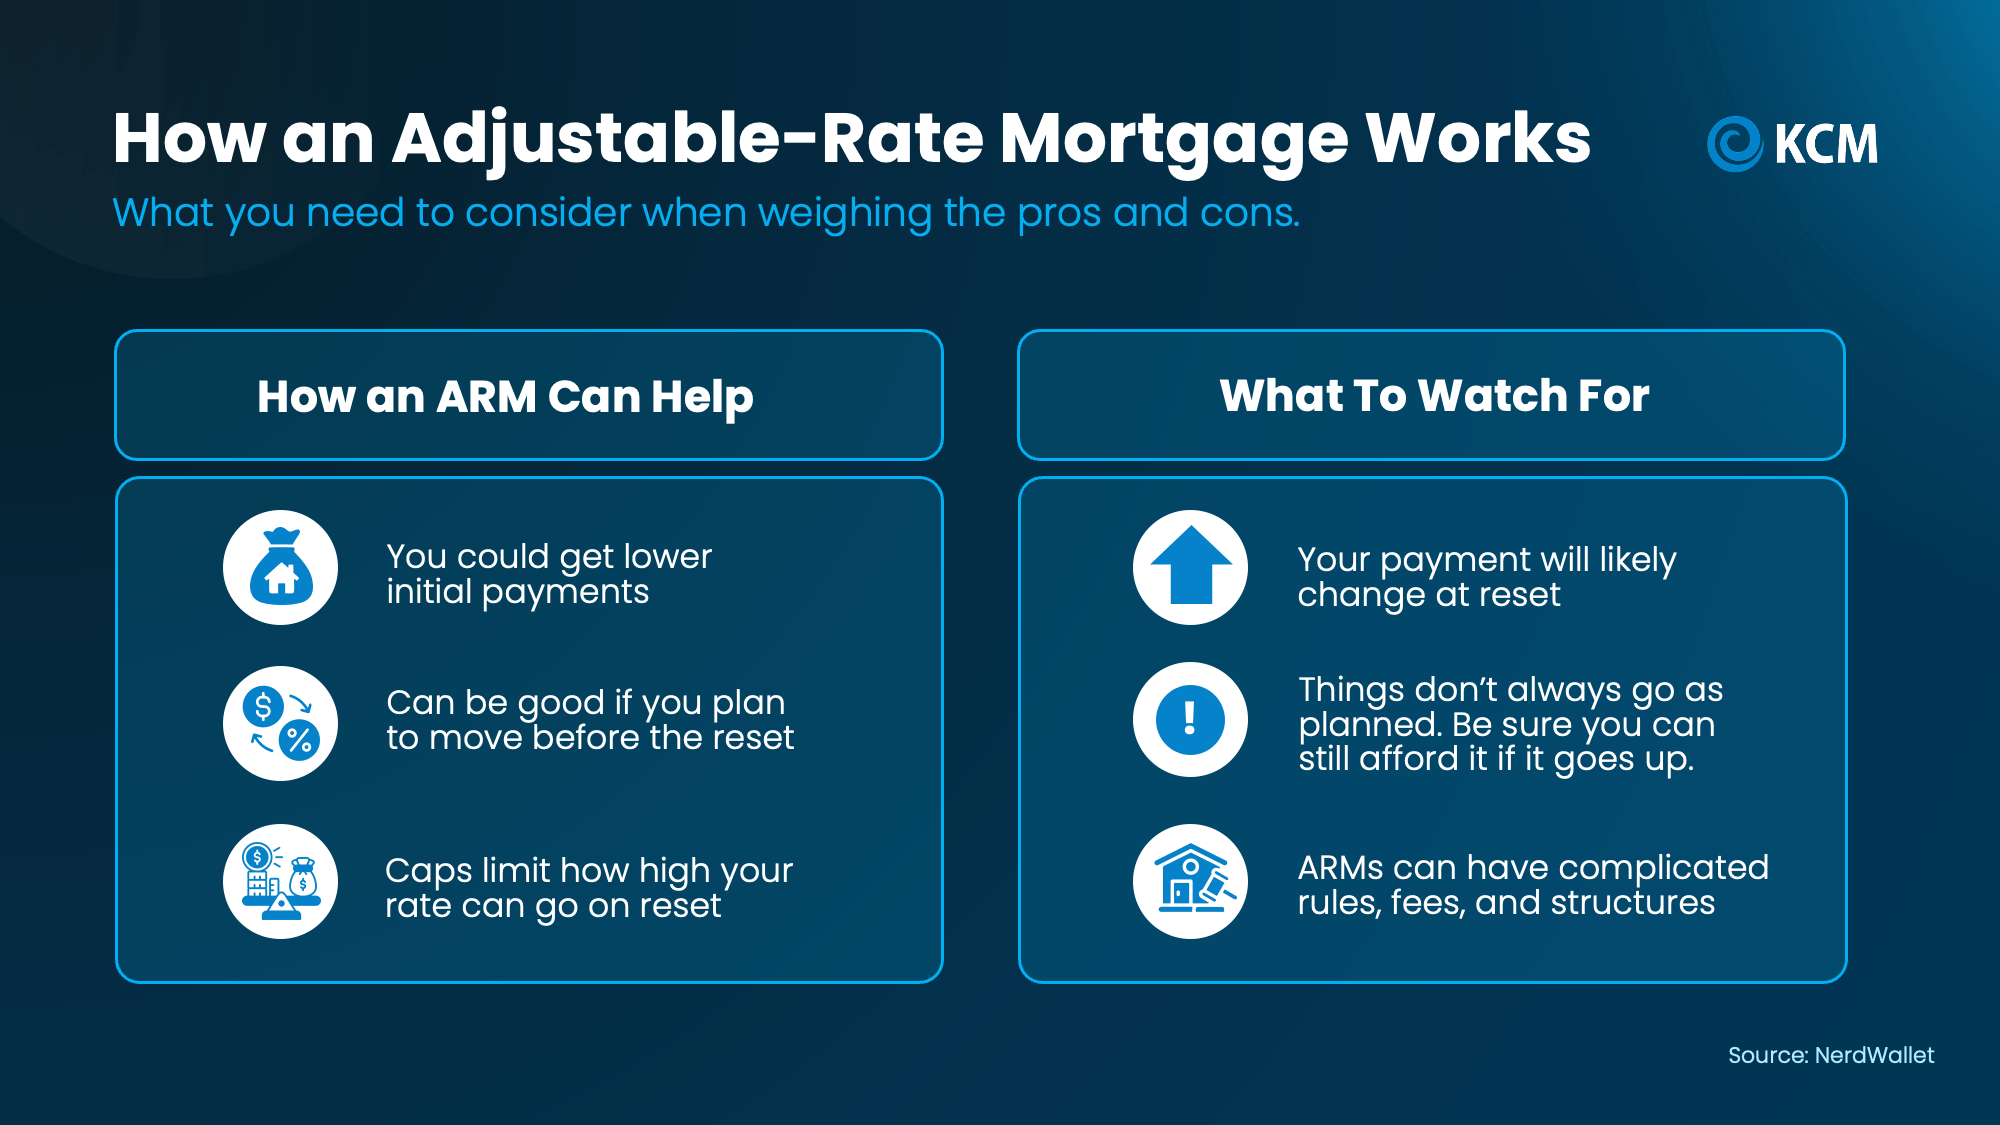
Before you decide, ask your lender to work up the numbers and walk you through the different potential scenarios you could run into with an ARM. That way, you go in with your eyes open.
Be Ready for the Reset
And, if you do go with an adjustable-rate mortgage, just know that you'll have choices when the reset time arrives. You could:
-
Do nothing and keep your loan in place if the new payment still fits your budget.
-
Refinance into a fixed-rate loan with a payment that never changes.
-
Refinance into another ARM with a new lower rate locked for a specified timeframe.
-
Sell your home.
-
Talk to the loan servicer about assistance or modification.
Remember, a refinance is a brand-new loan that you'll have to qualify for - even if it's on a home you already own. So, keep tabs on your credit and debt levels and ask your loan officer how major financial moves like job changes and major purchases will affect your mortgage readiness. It's important to keep your credit and finances in "mortgage shape."
Today’s ARMs Aren’t Like 2008
One more quick note. ARMs got a bad name after the financial crisis of 2008. Back then, there were some risky loans with small starting payments that later shot way up. Others let people borrow without proving how much money they earned.
But now, there are new laws to protect both borrowers and lenders. The biggest change is the Ability-to-Repay Rule, which says that before a lender makes a home loan, it has to check real paperwork (like pay stubs, W-2 forms, and tax returns) to make sure you can afford it. The lender also has to look at what your payment could be after the reset, not just the low starting payment.
So, you don’t have to worry that today’s ARMs are the same as the ones we saw back during the crash.
Bottom Line
Today's market has more options than many people realize. Finding the right one could be as simple as getting more information about tools like ARMs. A trusted lender can run the numbers with you, walk you through the what-ifs, and help you explore the possibilities.
Categories
- All Blogs (196)
- Credit Scores & First-Time Home Buyers (1)
- Emotional Value of Homeownership (1)
- First-Time Buyer Guidance (1)
- First-Time Home Buyers & Affordability (1)
- First-Time Home Buyers & Affordable Housing (1)
- First-Time Homebuyers (12)
- First-Time Homebuyers & Affordability (1)
- First-Time Homebuyers & Market Trends (1)
- Home Affordability & Relocation (1)
- Home Buying (5)
- Home Buying & Down Payment Strategy (1)
- Home Buying & Housing Market (1)
- Home Buying & Real Estate Strategy (1)
- Home Buying & Remote Work (1)
- Home Buying & Selling (1)
- Home Buying & Selling | Mortgage Rates | Real Estate Market (1)
- Home Buying & Selling Strategy (1)
- Home Buying & Selling Tips (1)
- Home Buying Preparation (1)
- Home Buying Strategy (1)
- Home Buying Tips (11)
- Home Buying Trends (1)
- Home Buying Trends & Strategies (1)
- Home Equity (2)
- Home Equity & Selling (1)
- Home Financing / First-Time Buyers (1)
- Home Prices & Buyer Opportunities (1)
- Home Prices & Housing Market (1)
- Home Prices & Housing Market Trends (1)
- Home Prices & Market Trends (2)
- Home Prices & Real Estate Market (1)
- Home Seller Motivation (1)
- Home Selling (3)
- Home Selling & Fall Real Estate (1)
- Home Selling & Home Value (1)
- Home Selling & Housing Market (1)
- Home Selling & Housing Market Trends (1)
- Home Selling & Market Trends (1)
- Home Selling & Negotiation Strategies (1)
- Home Selling & Pricing Strategy (1)
- Home Selling & Real Estate Tips (1)
- Home Selling & Staging Tips (1)
- Home Selling Advice (4)
- Home Selling Strategy (1)
- Home Selling Tips (15)
- Home Selling Tips & Market Trends (3)
- Homebuyer Guides (1)
- Homebuyer Tips (2)
- Homebuying & Affordability Solutions (1)
- Homebuying Tips (1)
- Homeownership & Real Estate Investment (1)
- Homeownership Costs (1)
- Homeownership Tips (1)
- Housing Affordability & Mortgage Rates (1)
- Housing Inventory & Mortgage Rates (1)
- Housing Market & Foreclosure Trends (1)
- Housing Market & Home Buying (4)
- Housing Market & Home Selling (1)
- Housing Market & Home Values (1)
- Housing Market & Homeowner Equity (1)
- Housing Market Forecast (2)
- Housing Market Forecast & Real Estate Trends (1)
- Housing Market Insights (8)
- Housing Market Tips (1)
- Housing Market Trends (4)
- Housing Market Updates (23)
- Inflation, Mortgage Rates & Housing Market (1)
- Life Transitions & Homebuying Decisions (1)
- Luxury Real Estate (1)
- Market Trends & Forecasts (1)
- Market Trends & Insights (1)
- Market Update (1)
- Mortgage & Affordability (1)
- Mortgage & Finance (1)
- Mortgage & Financing (1)
- Mortgage & Home Buying (1)
- Mortgage & Interest Rates (1)
- Mortgage Options & Home Financing (1)
- Mortgage Rates & Federal Reserve (1)
- Mortgage Rates & Home Buying (1)
- Mortgage Rates & Home Buying Strategy (3)
- Move-Up Buyers (1)
- Moving & Selling Tips (1)
- New Construction (1)
- New Construction & Home Buying (2)
- New Construction & Homebuying (1)
- Real Estate / Housing Market (1)
- Real Estate Investing (1)
- Real Estate Market Insights & Homebuying (1)
- Real Estate Market Trends (1)
- Real Estate Market Update (5)
- Real Estate Trends (2)
- Retirement & Housing Decisions (1)
- Retirement & Real Estate (1)
- Seasonal Real Estate Trends (1)
- Seller Education & Market Insights (1)
- Selling a Home & Housing Market (1)
- Selling a Home & Rental Property (1)
- Selling Tips (2)
- Senior Living & 55+ Communities (1)
- Senior Living & Downsizing (1)
- Strategy & Re-listing Tips (1)
- VA Loans & Veteran Homebuying (1)
Recent Posts
Associate Broker License ID: BR526609000
+1(602) 342-8006 | andrewm@themonaghangroup.com